Buying a Home in Albuquerque With a Cash Offer: Creative Financing Explained
Suggested URL Slug: buying-home-albuquerque-cash-offer
Does “cash offer” mean you must have the full purchase price in your bank account? Not always. When buying a home in Albuquerque with a cash offer, the phrase may describe how the seller is paid, not how the buyer funds the purchase. That distinction matters when financing or other parties are involved.
Before you commit, clarify whether the offer is truly all cash or whether financing is part of the arrangement. These paths can involve different obligations, timelines, and risks. The label alone won’t tell you which applies or whether the terms fit your finances.
This guide explains the difference and compares creative financing paths buyers may encounter, including seller financing. You’ll learn what to verify about funding, payment terms, contingencies, title, and responsibilities. Mountain View Realty LLC’s Robb Krautbauer brings 15 years of real estate investing experience and 10 years as a licensed agent to conversations about buyer options. The aim is a clear Albuquerque home-buying plan, with terms verified by the appropriate professionals and no pressure to choose a particular path.
Key Takeaways
- Buying a home in Albuquerque with a cash offer doesn’t automatically mean you must fund the entire purchase yourself. Confirm who provides the money and how the seller will be paid.
- Compare an all-cash purchase, a standard mortgage, and any available alternative structure against your budget, ownership plans, and comfort with risk.
- Before pursuing creative financing, clarify the structure and verify the written terms, contingencies, and responsibilities.
- Ask qualified New Mexico professionals to review legal, tax, title, and lending details before you commit.
- Mountain View Realty LLC can help you examine options and prepare questions, but it isn’t a direct mortgage lender.
Buying a Home in Albuquerque With a Cash Offer: What Does It Actually Mean?
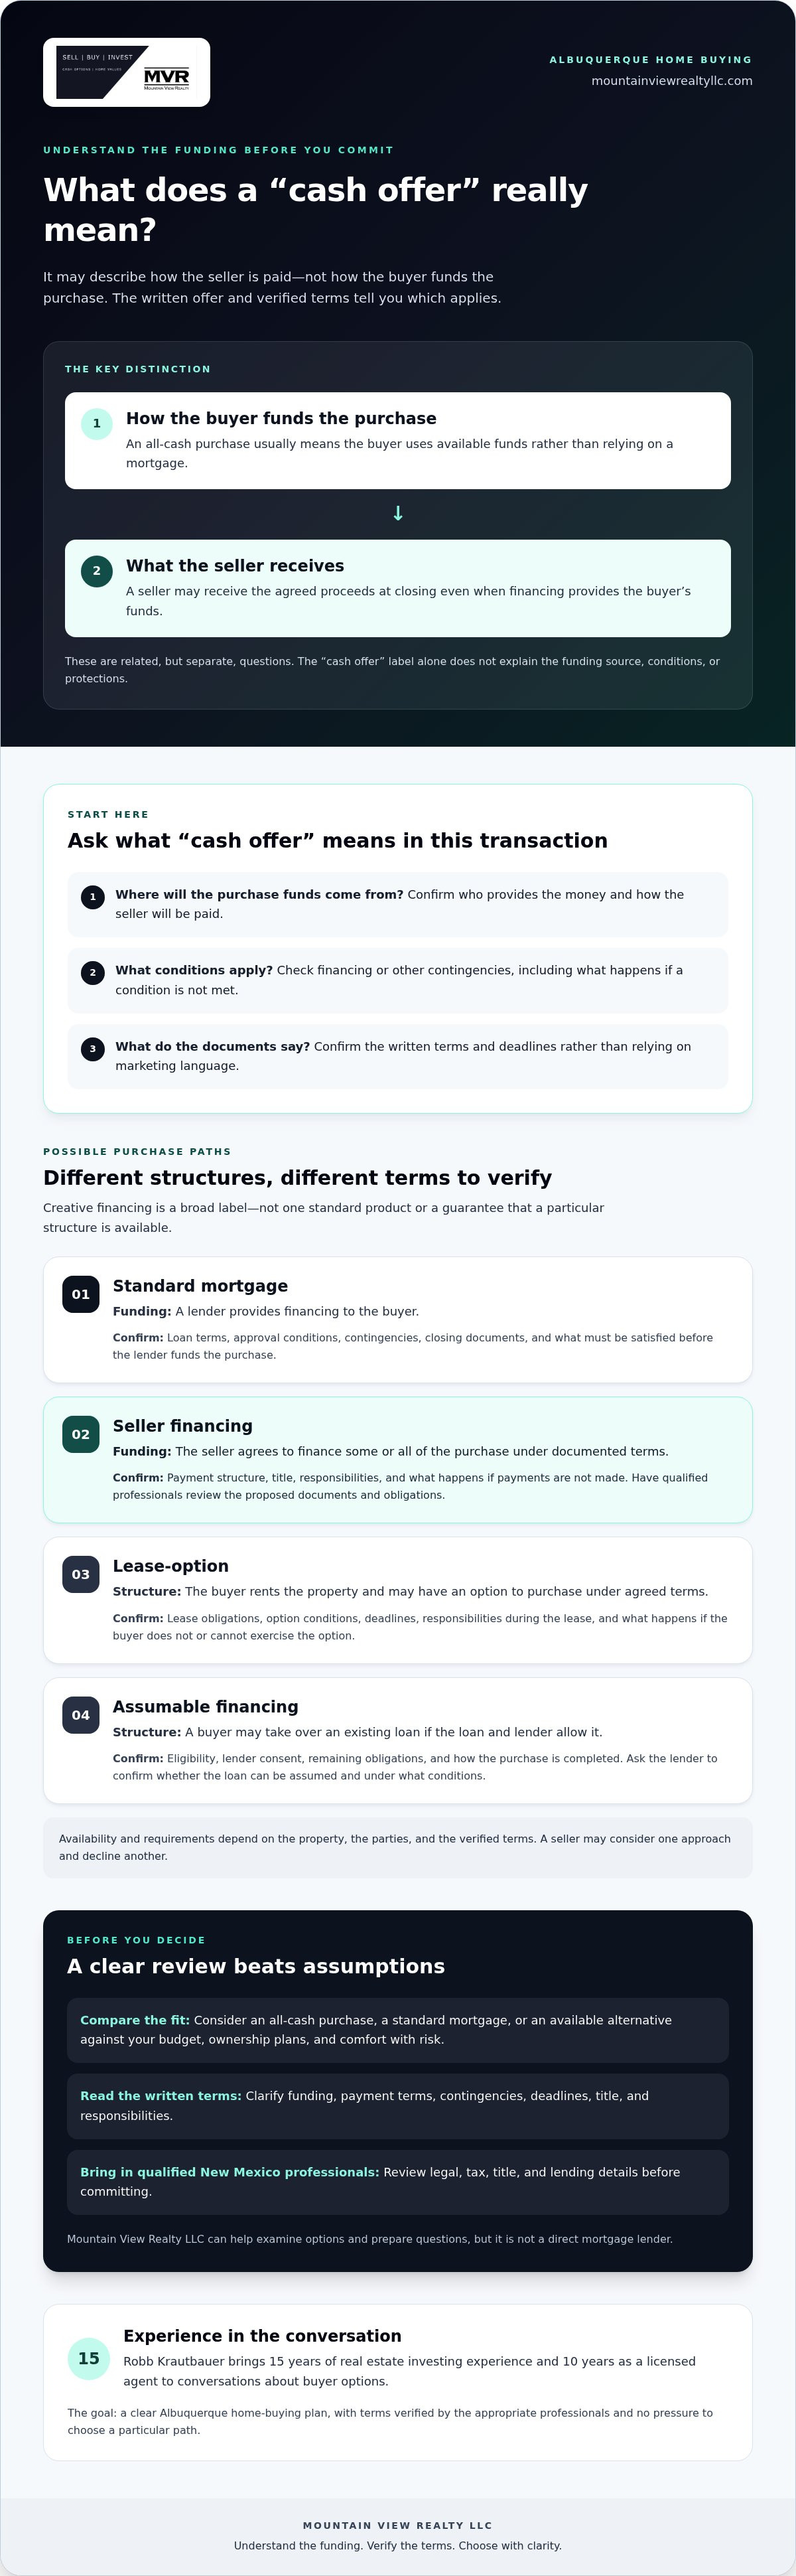
A cash purchase usually means the buyer pays from available funds rather than using a mortgage. But a seller receiving cash proceeds doesn’t necessarily mean the buyer paid entirely in cash. A buyer may use financing to provide the funds the seller receives at closing. The written offer explains how the purchase is funded and what conditions apply.
This distinction is central to buying a home in Albuquerque with a cash offer. The phrase may refer to the buyer’s funding method or describe what the seller expects to receive. From the buyer’s perspective, the key questions are where the purchase funds come from, what conditions must be met, and what the documents actually say.
Does a cash offer mean the buyer pays entirely in cash?
In everyday use, “all cash” generally means the buyer isn’t relying on a mortgage to complete the purchase. A cash offer may still include conditions, so the label doesn’t tell you whether protections have been waived or what happens if a condition isn’t met.
Marketing language can be less precise than the purchase documents. A buyer might describe an offer as “cash” because the seller would receive funds at closing, even though the buyer expects financing to provide those funds. Before relying on that description, confirm the funding sources, any financing or other contingencies, and the deadlines in the transaction documents.
Why Albuquerque buyers may encounter different meanings
Consider a hypothetical buyer looking at a home in Albuquerque. They might have enough funds to make an all-cash purchase, or they might plan to use a mortgage or another financing arrangement. From the seller’s perspective, the focus may be on receiving the agreed proceeds at closing. These are related but separate questions.
Alternative arrangements can fall under the broad label of creative financing, which includes different ways a real estate purchase might be funded. The term doesn’t identify one standard product or mean a structure is available for a particular home. A seller may consider one approach and decline another, so confirm the proposed arrangement and terms with the parties involved.
The practical takeaway is simple: ask what “cash offer” means in this specific transaction. If financing is involved, understand how it affects the offer’s conditions and deadlines. Availability and details depend on the verified terms and the parties involved. Before deciding, have qualified professionals review relevant lending, legal, tax, and title questions.
How Creative Financing for Home Buyers Can Differ From a Standard Mortgage
Creative financing is a broad label for ways to structure a real estate purchase outside a standard mortgage. It isn’t one loan, a guarantee of approval, or a solution for every buyer. With a standard mortgage, a lender reviews the application and provides funds under agreed loan terms. Other arrangements may involve the seller, an existing loan, or a lease agreement. Availability and requirements depend on the property, the parties, and the verified terms.
| Possible path | Funding source and parties | Terms to confirm | Questions for an adviser |
|---|---|---|---|
| Standard mortgage | A lender provides financing to the buyer. | Loan terms, approval conditions, contingencies, and closing documents. | What must be satisfied before the lender funds the purchase? |
| Seller financing | The seller agrees to finance some or all of the purchase under documented terms. | Payment structure, title, responsibilities, and what happens if payments aren’t made. | Have qualified professionals reviewed the proposed documents and obligations? |
| Lease-option | The buyer rents the property and may have an option to purchase under agreed terms. | Lease obligations, option conditions, deadlines, and responsibilities during the lease. | What happens if the buyer doesn’t or can’t exercise the option? |
| Assumable financing | A buyer may take over an existing loan if the loan and lender allow it. | Eligibility, lender consent, remaining obligations, and how the purchase is completed. | Has the lender confirmed the loan can be assumed and under what conditions? |
What options might buyers ask about?
These examples aren’t interchangeable. Seller financing requires the seller’s agreement. A lease-option combines a lease with a possible future purchase, subject to its written conditions. Assuming a loan depends on the loan’s terms and may require lender consent. Don’t assume any structure is available for a specific Albuquerque home. Verify current eligibility and ask qualified New Mexico legal, lending, title, and tax professionals to review relevant requirements before proceeding.
What should buyers compare beyond the monthly payment?
For anyone buying a home in Albuquerque with a cash offer, the monthly amount alone won’t show the full picture. Review total obligations, payment structure, contingencies, and what happens when an agreement ends. Clarify in writing who holds title and who handles insurance, maintenance, and default-related responsibilities, where applicable.
The Consumer Financial Protection Bureau’s home-buying tools and guidance can help you prepare questions about mortgages and closing documents. You can also discuss Albuquerque home-buying options with Mountain View Realty LLC. The firm isn’t a direct mortgage lender, and any financing structure must be confirmed on its own terms.
Cash Offer vs. Creative Financing: Which Albuquerque Buying Path Fits?
No single path suits every buyer. An all-cash purchase uses the buyer’s available funds. A standard mortgage relies on lender financing and its review process. Creative financing can involve different parties and obligations, so its availability and terms must be confirmed for the specific transaction.
For a buyer considering buying a home in Albuquerque with a cash offer, the useful comparison goes beyond the monthly payment. Consider your available funds, how much flexibility you need, the documentation required, your comfort with uncertainty, and how long you expect to own the home. Use the table to guide your review, not to predict savings or results.
| Path | Potential advantages | Trade-offs to consider | Questions to ask |
|---|---|---|---|
| All-cash purchase | No mortgage financing is planned for the purchase. | Uses available funds, and the offer still needs clear terms and verified funds. | What funds will be used, and what conditions and deadlines are written into the offer? |
| Standard mortgage | A lender-led process can provide defined documentation and loan terms to review. | Approval and funding depend on lender review and the buyer’s circumstances. | Have I compared lender terms and confirmed my full purchase budget? |
| Creative financing | A different structure may be worth exploring if the parties agree and it fits the buyer’s plans. | Terms, responsibilities, and availability can vary; additional review may be needed. | Will the seller agree, and have qualified professionals reviewed every material term? |
When a conventional mortgage may be the clearer route
A mortgage may suit buyers who want to compare lender-provided terms and follow a financing process with documented requirements. That doesn’t guarantee approval or make a mortgage simpler or less costly than another option. Compare lender terms, account for your complete budget, and understand any financing conditions before making an offer.
When to investigate a nontraditional structure
You might explore another structure if you need flexibility a standard mortgage may not provide or your ownership plans call for a different arrangement. For example, seller financing requires the seller’s agreement. Confirm the seller’s willingness and the written terms before relying on this or any other option. The proposed structure determines which lender, title, legal, tax, and contract reviews may be relevant.
Mountain View Realty LLC’s comparison of an Albuquerque home trade-in and traditional sale explains transaction alternatives. It isn’t an offer of buyer financing. Use it as a separate point of reference while weighing your purchase path and verifying the terms that apply to you.
A Practical Checklist for Evaluating Creative Financing in Albuquerque
Before considering a nontraditional arrangement, get clear on your priorities. Set a purchase budget, decide how long you expect to own the property, and identify how much flexibility and uncertainty you’re comfortable with. Then work through these steps.
- 1. Clarify the structure. Ask what type of arrangement is proposed, who provides the funds, and which parties must agree. Don’t rely on a label alone.
- 2. Verify the funds. Confirm where the purchase funds will come from and how payments will be made. If a lender or another funding source is involved, ask what must be confirmed before you rely on it.
- 3. Review the written terms. Check payment obligations, contingencies, deadlines, and what happens if a condition isn’t met or the arrangement ends. Request written clarification for anything unclear.
- 4. Assess the risks and responsibilities. Ask who will hold title and who is responsible for insurance, maintenance, and default-related obligations, where applicable. Consider whether the terms match your ownership plans and comfort with uncertainty.
- 5. Consult qualified professionals. Ask which lending, legal, title, or tax professionals should review the proposed documents. Confirm which contingencies and deadlines apply to your transaction.
Keep this principle in mind: Don’t rely on a verbal summary when written terms remain unclear. Ask questions, get answers in writing, and check those answers against the current transaction documents.
Questions to ask before making or accepting an offer
Who provides the funds? How will payments work? What could change or end the arrangement? Which contingencies and deadlines apply? Who should review the documents? If you’re buying a home in Albuquerque with a cash offer, clear answers help distinguish a general description from the terms actually proposed.
Local details to verify in Bernalillo and Sandoval Counties
Property and transaction details can vary. Confirm relevant property and title information with appropriate local professionals rather than assuming the same rule applies throughout Albuquerque and nearby communities. If your move also involves selling a current home, Mountain View Realty LLC’s Albuquerque home-buying and selling strategy guide may help clarify related transaction choices.
For an educational conversation about your Albuquerque purchase options, Mountain View Realty LLC can help you identify questions to explore. The firm isn’t a direct mortgage lender, and proposed financing terms should be independently verified.
Plan Your Albuquerque Home Purchase With Clear Advice, Not Assumptions
A “cash offer” can mean different things depending on how the buyer plans to fund the purchase and what the written terms say. Before choosing a path, make sure you understand who provides the funds, what conditions apply, and what responsibilities you would take on. Clear answers are more useful than assumptions about what a label promises.
Mountain View Realty LLC is a real estate brokerage and adviser, not a direct mortgage lender. Robb Krautbauer brings 15 years of real estate investing experience and 10 years as a licensed agent. That background can inform a conversation about your options, but it doesn’t guarantee a specific financing structure will be available or that a purchase will proceed a certain way. Financing and transaction terms need to be verified for your situation.
What a planning conversation can help clarify
A useful discussion starts with your goals and the details that remain uncertain. Are you considering an all-cash purchase, a mortgage, or another structure? How long do you expect to own the home? Which terms, responsibilities, or deadlines need more explanation? Your answers can help you prepare questions for a lender, legal adviser, title professional, or other qualified expert.
For buyers exploring buying a home in Albuquerque with a cash offer, keep the conversation grounded in your priorities and the current transaction documents. An adviser can help organize questions and compare possible paths, while qualified professionals review matters within their areas of expertise. There’s no need to settle on a structure before its availability and terms are clear.
A low-pressure next step for Albuquerque buyers
If you’re weighing your options, bring your questions and any proposed terms to a planning conversation. Use the time to identify what you know, what needs verification, and which professional can address each open question. The aim is a more informed next step, not a promise of approval, financing, or a particular purchase outcome.
Grab a time on my calendar, no pressure, just a plan for your next move. You’re welcome to schedule a no-pressure planning conversation about your goals and questions.
Robb Krautbauer, Owner & Qualifying Broker
Move Forward With a Clear Plan for Your Albuquerque Purchase
Buying a home in Albuquerque with a cash offer starts with understanding exactly what the phrase means in your transaction. A cash purchase uses the buyer’s funds, while a seller receiving cash proceeds may still involve buyer financing. The funding source, written terms, contingencies, and responsibilities matter more than the label.
Compare an all-cash purchase, a standard mortgage, and any available alternative structure against your budget, ownership plans, and comfort with risk. Before committing, verify the terms and ask qualified professionals to review relevant lending, legal, tax, and title questions. No single path fits every buyer.
Robb Krautbauer brings 15 years of real estate investing experience and 10 years as a licensed agent to buyer conversations. Mountain View Realty LLC has helped 200+ families and investors buy and sell across the Albuquerque metro. The firm can help you examine options and organize questions, but it isn’t a direct mortgage lender and can’t guarantee financing or a purchase outcome.
With clear information and the right professional input, you can choose your next step with greater confidence.
Frequently Asked Questions
Does buying a home with a cash offer mean I need to pay all cash?
Not necessarily. An all-cash purchase generally means the buyer uses available funds rather than a mortgage. But “cash offer” may also describe a seller receiving cash proceeds at closing, even if the buyer uses financing to provide those funds. If you’re buying a home in Albuquerque with a cash offer, check the written offer for its funding source, conditions, contingencies, and deadlines. The phrase alone doesn’t explain the full arrangement.
Can I buy a home in Albuquerque with creative financing instead of a mortgage?
Possibly, but creative financing isn’t one standard loan or a guaranteed option. Depending on the property and parties involved, buyers might ask about seller financing, a lease-option, or assuming an existing loan. Each has different terms and may require agreement from the seller or lender. Confirm whether a structure is available for the specific home, and ask qualified New Mexico professionals to review relevant lending, legal, tax, title, and contract details.
What is the difference between a cash offer and seller financing?
A cash offer generally describes how a purchase is funded or how the seller expects to receive proceeds. Seller financing describes a possible funding arrangement in which the seller agrees to finance some or all of the purchase under written terms. They aren’t interchangeable. A buyer may use seller financing, but the phrase “cash offer” doesn’t establish that this is the arrangement. Review the written documents to identify the funding source and obligations.
Is seller financing available for homes in Albuquerque?
Seller financing may be an option in New Mexico, but it isn’t available for every Albuquerque home. The seller must be willing to consider it, and property circumstances, existing financing, and applicable requirements may affect whether it can proceed. Don’t assume an advertised “cash offer” means the seller will finance the purchase. Verify current availability and proposed terms for the property, and have qualified professionals review the documents before you commit.
What should I check before agreeing to creative home financing?
Clarify who provides the funds, how payments work, and what conditions or deadlines apply. Review the full payment structure, contingencies, responsibilities for title, insurance, and maintenance where relevant, and what happens if the agreement ends or a payment obligation isn’t met. Ask for unclear points in writing and compare those answers with the current transaction documents. A qualified lender, legal adviser, title professional, or tax professional can review questions within their expertise.
Can Mountain View Realty provide a loan or guarantee a cash offer?
No. Mountain View Realty is a real estate brokerage, not a direct mortgage lender, and it doesn’t guarantee financing, approval, or a purchase outcome. The firm can help buyers examine possible paths and identify questions to verify, but any loan or creative-financing terms must be confirmed with the relevant parties and qualified professionals. For an Albuquerque purchase, rely on the written transaction documents and lender confirmation where applicable, not an informal description of the offer.
How do I compare a mortgage with a creative financing option?
Compare more than the monthly payment. Consider your available funds, total obligations, documentation, contingencies, responsibilities, and what happens at the end of the agreement. A mortgage involves lender review and loan terms; a creative arrangement may involve different parties and risks. Ask whether the seller agrees, verify any required lender consent, and have qualified professionals review the specific terms. The right comparison depends on your budget, ownership plans, and comfort with uncertainty.
Article by
Robb Krautbauer
Robb Krautbauer is the Owner and Qualifying Broker of Mountain View Realty, serving Albuquerque, Rio Rancho, Santa Fe, and surrounding New Mexico communities. With more than a decade of real estate experience, Robb specializes in luxury homes, strategic home marketing, and helping homeowners navigate important life transitions with confidence.
Known for combining luxury-level marketing, AI-powered technology, and innovative selling strategies, Robb helps clients maximize their home's value while creating a smooth, personalized selling experience. Whether assisting luxury homeowners, retirees, families downsizing, or real estate investors, his focus is always on delivering expert guidance, honest advice, and exceptional results.
When he's not helping clients achieve their real estate goals, Robb enjoys studying market trends, emerging technology, and investment strategies that keep Mountain View Realty at the forefront of the industry.
Disclaimer
**Disclaimer:** The information provided in this article is for general educational purposes only and should not be considered legal, tax, financial, or professional advice. Real estate laws, market conditions, and regulations change over time and may vary based on your individual circumstances. Before making any real estate decision, consult with qualified legal, tax, or financial professionals. If you have questions about buying or selling real estate in New Mexico, contact Mountain View Realty for guidance specific to your situation. © 2026 Mountain View Realty. All rights reserved. The content on this website may not be reproduced without written permission.


