How to Avoid Two Mortgage Payments When Buying a New Home: A 2026 Strategy Guide
Imagine you just found your next home in Sandia Heights or Corrales. It has the view you've always wanted and the space you need. But there's a problem. Your current house hasn't sold yet. For many homeowners, this realization brings an immediate sense of dread. You don't want to lose a great property to a non-contingent buyer, yet the thought of carrying two high-interest monthly payments is a financial nightmare. It's a common dilemma in a 2026 market where 30 year fixed rates sit near 6.76 percent.
You deserve a transition that feels like a step forward, not a source of constant anxiety. We believe that protecting your hard-earned equity should be simple and stress-free. This guide will show you exactly how to avoid two mortgage payments when buying a new home using strategic transaction paths and modern financial tools. You'll discover how to make a competitive offer that wins in Albuquerque's most desirable neighborhoods without the risk of financial ruin. We will walk through the specific options that allow you to buy first and sell later, ensuring a seamless move that respects your timeline and your peace of mind.
Key Takeaways
- Learn how to present a "contingency-free" offer that competes with cash buyers in exclusive Albuquerque neighborhoods like Sandia Heights.
- Discover how financial bridge tools like HELOCs can unlock your current equity to secure your next property before you list.
- Explore modern programs like Home Trade-In and CashOffer+ to help you avoid two mortgage payments when buying a new home during your transition.
- Understand the risks of traditional sale contingencies and why luxury sellers in Corrales often prioritize offers without them.
- Gain strategic insights on protecting your hard-earned equity through expert pricing and a methodical, stress-free moving timeline.
The Financial Risk of the 'Buy-Sell' Overlap in Albuquerque
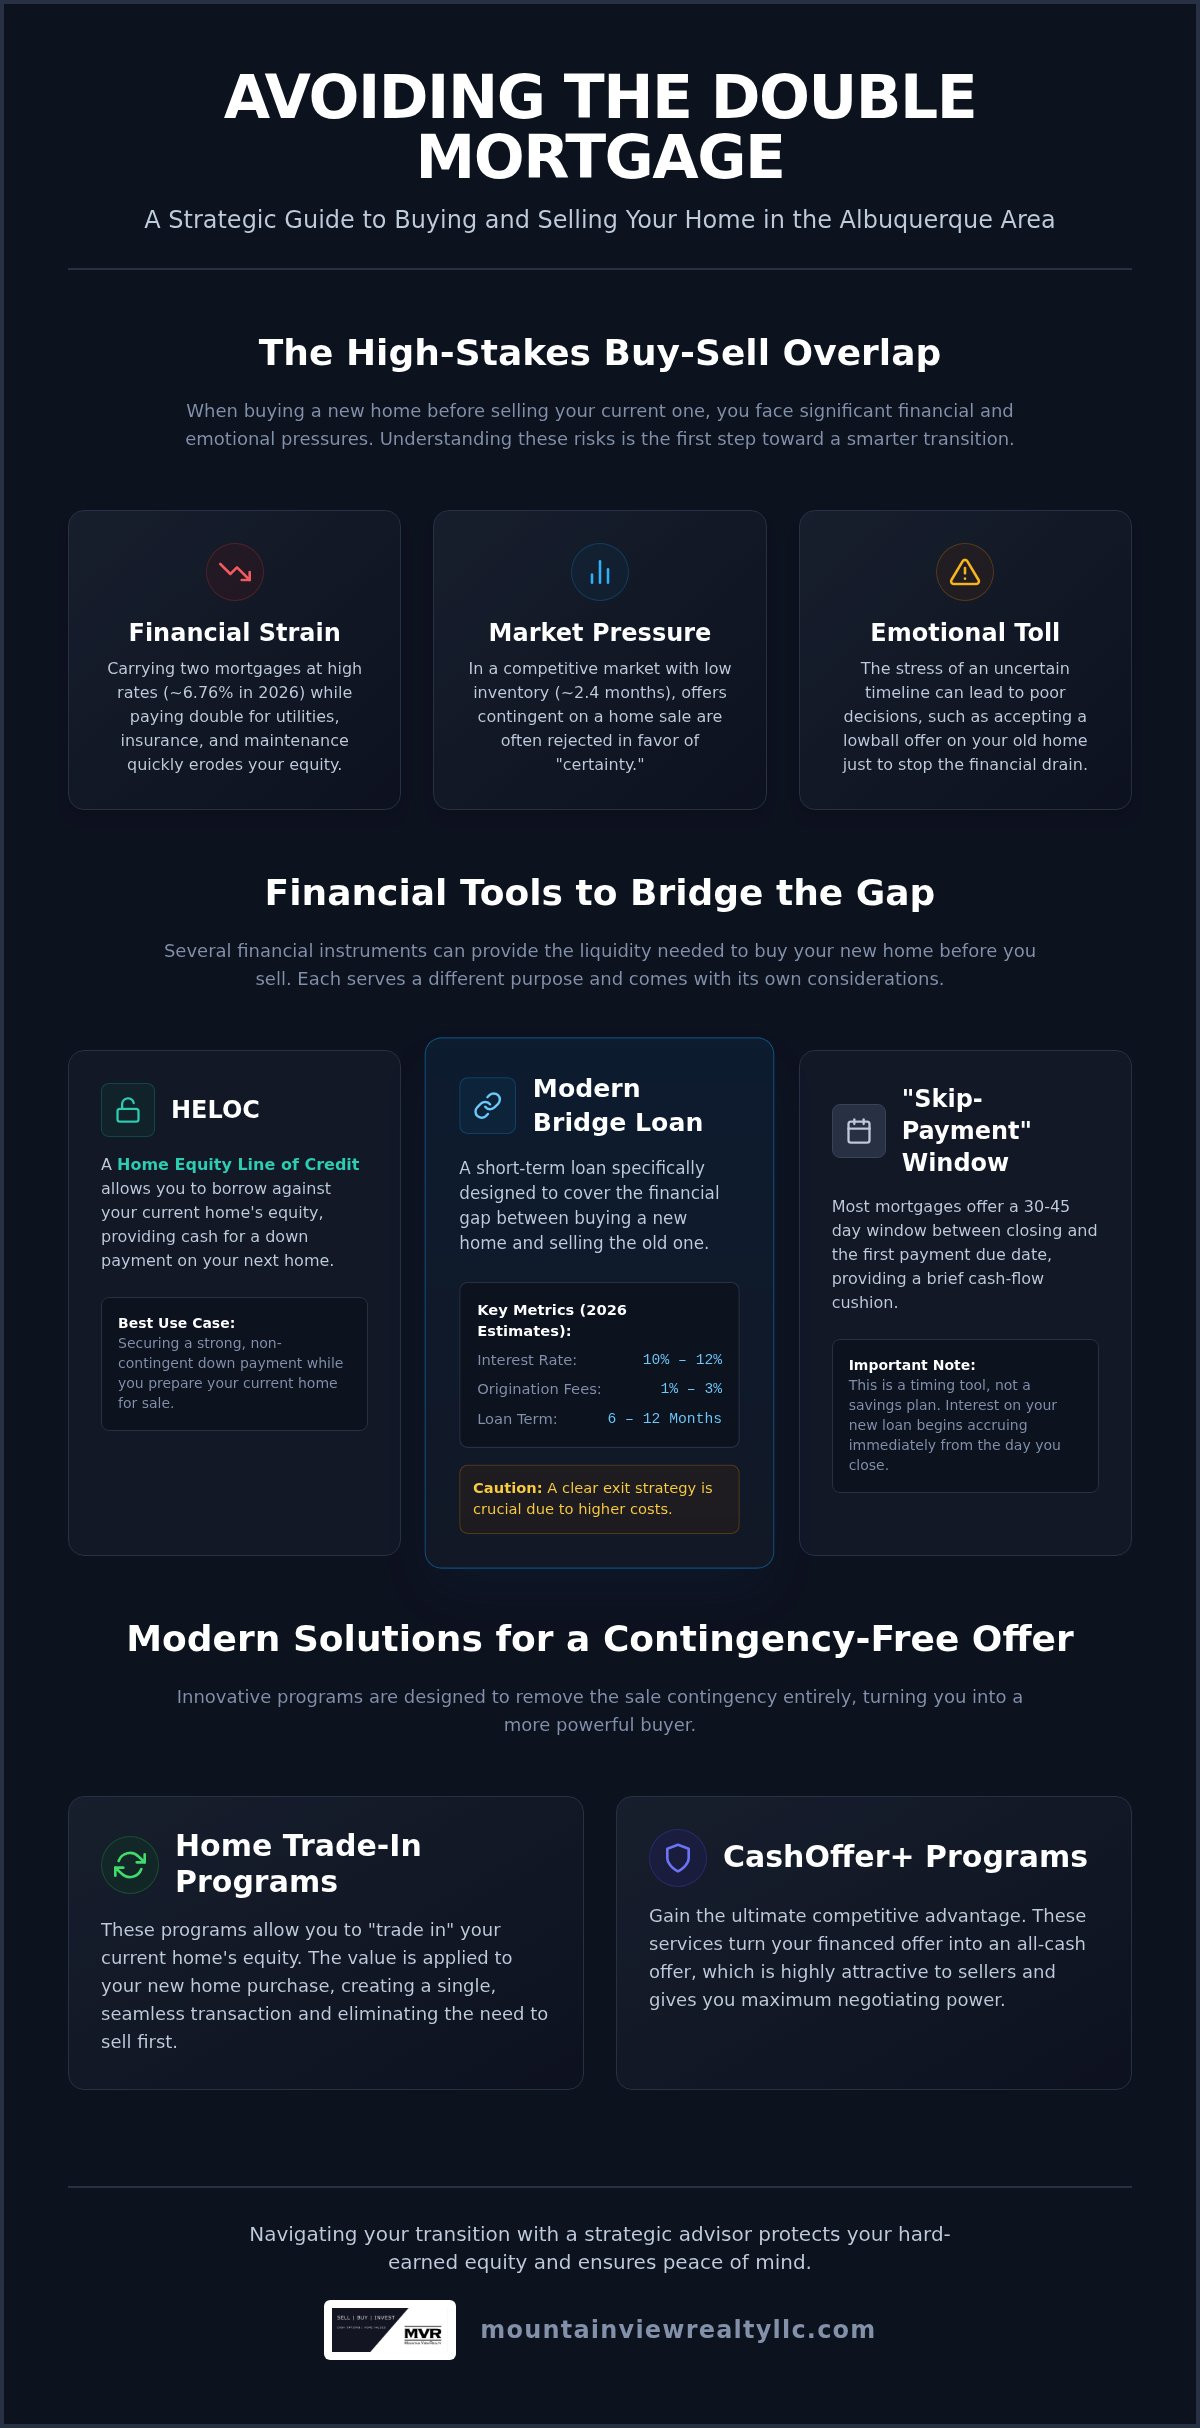
Carrying two mortgages isn't just a line item on a spreadsheet. It's a weight that follows you through every room of your new house. For many homeowners in the Albuquerque metro, the excitement of a new purchase is quickly overshadowed by the psychological toll of the "overlap." You find yourself checking your bank balance daily, wondering when the first home will finally close. This stress often leads to rushed decisions, such as accepting a lowball offer on your previous property just to stop the financial bleed. Strategic planning is the only way to avoid two mortgage payments when buying a new home while protecting your hard-earned equity.
The risks extend beyond the mortgage itself. Hidden costs accumulate quickly when a home sits vacant. You are responsible for double the utilities, double the property insurance, and ongoing maintenance. In New Mexico, keeping a vacant home's landscaping and cooling systems running is essential to maintain its value, but these costs eat into your profit every single day. Traditional simultaneous closings, where you sell and buy on the same day, are becoming increasingly unreliable. A single delay in an inspection or a buyer's financing can cause the entire "house of cards" to collapse, leaving you with two payments and a legal headache.
Why Albuquerque's 2026 Market Demands a Better Plan
The 2026 market in Sandia Heights and High Desert remains competitive. With inventory levels hovering around 2.4 months of supply, well-priced homes still attract multiple offers. If your offer includes a sale contingency, you are at a distinct disadvantage. Sellers in luxury neighborhoods often prioritize non-contingent offers, even if the price is slightly lower, because they want certainty. Many buyers try to bypass this by moving into a rental first, but this "Double Move" is a trap. Between storage fees, double moving truck rentals, and non-refundable deposits, you can easily spend thousands of dollars without making any progress toward your goal.
The Honest Reality of Carrying Two Payments
Before committing to an overlap, you must calculate your "Burn Rate." This is the total amount of cash you lose every month the old home remains unsold. With 30 year fixed rates near 6.76 percent, that number is likely higher than you expect. This overlap also impacts your Debt-to-Income (DTI) ratio. Lenders look at both payments when qualifying you for the new loan, which can limit your purchasing power or force you into higher-interest products like Bridge Loans. The buy-sell gap is the primary obstacle to luxury home transitions in 2026. Understanding these financial pressures is the first step toward choosing a more intelligent path.
Financial Bridge Tools: HELOCs, Bridge Loans, and Skip-Payments
Transitioning between luxury properties in the Albuquerque metro requires more than just a moving truck. It requires liquidity. Most homeowners have their wealth locked in their current residence, which makes it difficult to avoid two mortgage payments when buying a new home. Fortunately, several specialized financial tools can bridge this gap. These options allow you to leverage your existing equity to secure your next property before you even put a "For Sale" sign in your yard.
One common tactic is the skip-payment mechanic. Most lenders allow a gap between your closing date and your first mortgage payment, typically lasting 30 to 45 days. While some interpret this as "saving" money, it is actually a cash-flow management tool. Interest still accrues during this period, often at the standard 2026 rate of 6.76 percent for a 30 year fixed loan. It provides a brief window of relief, but it doesn't solve the underlying challenge of carrying two properties if the first one doesn't sell quickly.
Understanding the Modern Bridge Loan
As of 2026, bridge loans remain a popular choice for buyers in Sandia Heights who need to move quickly. These short term loans are designed specifically to cover the period between the purchase of a new home and the sale of the old one. Typical interest rates currently range from 10 percent to 12 percent, with origination fees often sitting between 1 percent and 3 percent. Because of these costs, having a clear exit strategy is vital. You must be confident in your home's marketability, as these loans usually have a six to twelve month term. If you are weighing your choices, comparing a Bridge Loan vs. HELOC is a smart first step to determine which cost structure fits your timeline.
HELOCs as a Strategic Down Payment Source
A Home Equity Line of Credit (HELOC) is often a more flexible alternative. With national average rates around 7.26 percent in September 2026, a HELOC allows you to withdraw only what you need for a down payment. However, timing is everything. You must secure the HELOC while your current home is still your primary residence and before you list it for sale. Lenders are often hesitant to approve lines of credit on properties already on the market. This tool offers the advantage of interest only payments during the transition, which keeps your monthly "burn rate" manageable. If you're unsure which path fits your equity position, a confidential consultation can help clarify your options and protect your financial interests.
Why Contingency Offers Often Fail (And What to Do Instead)
In the real estate world, a Hubbard Clause, or a "Sale and Settlement" contingency, is a safety net for the buyer. It states that you will only buy the new home if your current property sells by a specific date. While this provides peace of mind, it often acts as a red flag for sellers in competitive neighborhoods like North ABQ Acres or Corrales. Most sellers view these as "maybe" offers. To successfully avoid two mortgage payments when buying a new home, you need a strategy that doesn't rely on the seller's willingness to wait for your current house to close.
Sellers in 2026 are highly sensitive to risk. With recent data showing that 6% to 15% of home purchase contracts fail to close, adding a sale contingency only increases those odds. If your buyer's financing falls through, the seller's transition is also ruined. This uncertainty is why non-contingent offers are almost always preferred, even if the price is slightly lower. You need to position yourself as a sure thing rather than a complication.
The Seller's Perspective in Bernalillo County
Sellers fear the "domino effect." If one buyer's deal in the chain fails because of a low appraisal or an inspection issue, every subsequent deal in that chain collapses. This is why "Kick-Out Clauses" are so common in Albuquerque. These clauses allow the seller to keep their home on the market while they wait for you. If they receive a non-contingent offer, you are given a short window, usually 48 to 72 hours, to remove your contingency or lose the home. This puts you in a high-pressure situation where you might be forced to carry two loans before you're ready.
Strategies for Winning Without a Contingency
If you want to win without the risk of carrying two mortgages, consider a "Rent-Back" agreement. You sell your current home first to unlock your cash, but you negotiate a stay for 30 to 60 days after closing. This turns you into a cash-heavy, non-contingent buyer. Alternatively, a Home Trade-In program allows you to bypass the traditional market entirely by unlocking your equity before you list. A non-contingent offer can save a buyer 2-3% on the purchase price by increasing leverage. By removing the seller's risk, you gain the power to negotiate a better deal on the home you actually want.
Strategic Alternatives: Home Trade-In and CashOffer+ Programs
National lenders often focus on selling you more debt through bridge loans or HELOCs. While those tools have their place, they don't change the fundamental structure of your move. Strategic transaction models like a Home Trade-In or a guaranteed cash offer provide a different path. These programs are designed to avoid two mortgage payments when buying a new home by rearranging the sequence of your sale. Instead of hoping the timing works out, you use your current equity as a tool to secure your next property with total certainty.
Choosing a strategic sale model eliminates the "Double Move" trap. You won't need to find a temporary rental or pay for months of storage while waiting for a closing date. These solutions prioritize your cash flow and your peace of mind, allowing you to focus on the logistics of moving into your new Albuquerque home rather than the stress of a failing contingency.
The Home Trade-In Process Explained
A Home Trade-In program acts as a bridge for your equity, not just your mortgage. The process is straightforward and transparent. First, we conduct a professional valuation of your current property to determine its market value in the 2026 Albuquerque landscape. Next, a portion of that equity is unlocked, providing you with the funds needed for a down payment on your next home. Finally, you can make a cash-backed, non-contingent offer on your next property. This makes your bid significantly stronger in competitive areas like Sandia Heights, where sellers prioritize speed and reliability.
When CashOffer+ is the Right Move
Sometimes, the traditional MLS market doesn't fit your timeline. If you've already found your next home and need to act instantly, CashOffer+ is often the most efficient choice. This program provides a competitive cash offer for your current home, allowing you to close the gap between properties immediately. While homes on the Albuquerque market in 2026 average 30 to 45 days to sell, CashOffer+ can close in as little as 10 to 14 days. This speed gives you the leverage to negotiate as a cash buyer on your purchase. Learn more about CashOffer+ for your Albuquerque home to see if this accelerated path fits your goals.
If you prefer to take your time, the "Sell & Stay" option allows you to sell your home and rent it back. This keeps you in your familiar surroundings while you shop for your next residence. It effectively removes the pressure of a ticking clock, ensuring you only move once. By combining these strategic alternatives, you protect your equity and maintain control over your transition.
Navigating Your Transition with a Strategic Advisor
Choosing a path to avoid two mortgage payments when buying a new home is a complex financial decision that requires more than just a real estate license. It requires a strategic partner who views the transaction through an investor's lens. In exclusive New Mexico markets like Corrales, Placitas, and Sandia Heights, neighborhood dynamics can shift quickly. A strategic advisor doesn't just list your home; they protect your equity by analyzing real-time market data and timing your sale to your specific advantage. This level of local expertise ensures you don't leave money on the table in a rush to close the gap between properties.
The goal of a strategic transition is to move with confidence. This starts by creating a custom "Move Plan" that prioritizes your financial peace of mind. By mapping out every step, from the initial valuation to the final closing, you can eliminate the "what-ifs" that cause so much stress during a move. Whether you are navigating a luxury upgrade or a sensitive senior transition, having a clear roadmap allows you to make decisions based on facts rather than fear.
The Educator’s Approach to Your Next Move
Robb Krautbauer brings 15 years of investor experience and a decade as a licensed agent to every client relationship. Having helped over 200 families in the Albuquerque metro, he understands that every transition is unique. An educator’s patience is vital when discussing high-stakes real estate decisions. Instead of pushing for a quick sale, a strategic advisor takes the time to explain how different models affect your bottom line. Choosing a strategic real estate agent in Albuquerque means finding a partner who prioritizes your long-term financial health and provides the clarity needed for a seamless transition.
Taking the First Step Without Pressure
The first step toward your new home shouldn't feel like a sales pitch. During a confidential strategic consultation, the focus is entirely on your goals. We evaluate all available paths together, looking at the Traditional listing process, the Home Trade-In model, and the CashOffer+ program. We analyze your current equity, your target neighborhood's competitiveness, and your desired timeline. This data-driven approach ensures you choose the method that best protects your hard-earned equity while simplifying your move. This process is designed to empower you with choices rather than corner you into a single option.
Grab a time on my calendar — no pressure, just a plan for your next move.
Your Strategic Path to a Seamless Transition
Transitioning into your next property shouldn't feel like a high-stakes gamble with your home equity. By choosing a strategic path, you can move with the confidence that your finances are protected. Whether you utilize a Home Trade-In to unlock equity early or opt for the speed of CashOffer+, these modern solutions are designed to help you avoid two mortgage payments when buying a new home. You have the power to control your timeline rather than letting the market dictate your stress levels.
With 15 years of investor experience and over 200 families helped in the Albuquerque metro, I am here to ensure your move is both efficient and educational. We will look at the market data for your specific neighborhood to find the most profitable and stress-free path forward. Your next chapter in Sandia Heights or Corrales is waiting, and we have the tools to get you there without the burden of overlapping debt. You deserve a move that feels like a step forward.
Robb Krautbauer
Owner & Qualifying Broker, Mountain View Realty LLC
Frequently Asked Questions
Can I really buy a new house before selling my current one?
Yes, you can buy before selling by using alternative transaction models like the Home Trade-In or CashOffer+ programs. These options allow you to unlock your current equity to secure your next property without waiting for a traditional buyer. This strategy is particularly effective in competitive Albuquerque neighborhoods where sellers prioritize non-contingent offers. By removing the sale contingency, you become a stronger buyer while maintaining the flexibility to move on your own timeline.
What is a bridge loan and is it worth the cost in 2026?
A bridge loan is a short term financing tool that covers the financial gap between your new purchase and your old home's sale. In 2026, these loans typically carry interest rates between 10 percent and 12 percent, plus origination fees. For many in Sandia Heights, the cost is worth it to secure a specific property, but it's vital to have a clear exit strategy. We often compare these to other strategic paths to ensure you aren't overpaying for convenience.
How does a home trade-in program differ from a traditional sale?
A traditional sale requires you to list, show, and sell your home before you have the cash for your next purchase. A home trade-in program flips this sequence. You receive a professional valuation and unlock a portion of your equity immediately. This allows you to avoid two mortgage payments when buying a new home by making a cash-backed offer first. You move into the new house, and your previous home is sold afterward, often for a higher price.
What happens if my home doesn't sell after I buy a new one?
If you use a traditional bridge loan, you are responsible for both payments until the first home sells. However, programs like CashOffer+ provide a guaranteed backup. This eliminates the risk of being stuck with two high-interest payments indefinitely. We focus on strategic pricing and pre-market preparation to ensure your home attracts qualified buyers in the Albuquerque metro. Having a guaranteed exit strategy is the best way to protect your equity during a transition.
Is it better to sell first and rent, or buy first and carry two mortgages?
Selling first and renting often leads to a "double move," which increases costs and stress. Carrying two mortgages creates a high "burn rate" that can lead to rushed, poor financial decisions. A better alternative for many Albuquerque residents is the Sell & Stay program. This allows you to sell your home to unlock your cash but stay as a renter while you shop. It provides the liquidity of a sale without the logistical nightmare of moving twice.
How much equity do I need to qualify for a non-contingent buying program?
Most non-contingent programs require a minimum equity position, often starting around 20 to 30 percent of your home's current value. This equity serves as the collateral that allows you to avoid two mortgage payments when buying a new home while you transition. During a confidential consultation, we review your specific numbers and property value in areas like Rio Rancho or Corrales to determine which strategic path offers the most protection for your hard-earned wealth.
Are there specific programs for seniors transitioning to smaller homes in Albuquerque?
Seniors in the Albuquerque metro can benefit significantly from the Home Trade-In and Sell & Stay options. These programs are designed to reduce the physical and emotional stress of a transition by allowing for a slower, more methodical move. We specialize in senior transitions, focusing on protecting equity and coordinating the logistics of downsizing. Whether you are moving from a large estate in North ABQ Acres or a custom home in Placitas, we tailor the strategy to your timeline.
How do I avoid the 'double move' during a real estate transition?
You can avoid moving twice by using a rent-back agreement or a home trade-in model. These strategies allow you to stay in your current home until your new one is ready for move-in. By aligning the closing dates or utilizing a temporary lease, you move your belongings once. This approach saves thousands in storage and moving fees while keeping your family settled. It's a key part of any custom Move Plan we create for our Albuquerque clients.
Article by
Robb Krautbauer
Robb Krautbauer is the Owner and Qualifying Broker of Mountain View Realty, serving Albuquerque, Rio Rancho, Santa Fe, and surrounding New Mexico communities. With more than a decade of real estate experience, Robb specializes in luxury homes, strategic home marketing, and helping homeowners navigate important life transitions with confidence.
Known for combining luxury-level marketing, AI-powered technology, and innovative selling strategies, Robb helps clients maximize their home's value while creating a smooth, personalized selling experience. Whether assisting luxury homeowners, retirees, families downsizing, or real estate investors, his focus is always on delivering expert guidance, honest advice, and exceptional results.
When he's not helping clients achieve their real estate goals, Robb enjoys studying market trends, emerging technology, and investment strategies that keep Mountain View Realty at the forefront of the industry.
Disclaimer
**Disclaimer:** The information provided in this article is for general educational purposes only and should not be considered legal, tax, financial, or professional advice. Real estate laws, market conditions, and regulations change over time and may vary based on your individual circumstances. Before making any real estate decision, consult with qualified legal, tax, or financial professionals. If you have questions about buying or selling real estate in New Mexico, contact Mountain View Realty for guidance specific to your situation. © 2026 Mountain View Realty. All rights reserved. The content on this website may not be reproduced without written permission.


