How to Buy a House with No Money Down in New Mexico: A 2026 Guide
Suggested URL slug: /buy-house-no-money-down-new-mexico
Could the down payment be less of a barrier than you think, while closing costs still need a plan? If you're researching how to buy a house with no money down in New Mexico, the answer may depend on your military eligibility, the property’s location, your income, and the loan programs available to you. Zero-down financing can lower the cash needed upfront, but it doesn’t automatically mean you can buy with no money at closing.
It’s understandable to feel overwhelmed by program names and changing eligibility rules. The key is to separate true zero-down loans from down-payment assistance, which may help with upfront costs but has its own terms. Details can vary, so confirm current requirements with an approved lender or the official program source before building your budget around an option.
This guide explains the main paths to explore, including VA and USDA loans and New Mexico assistance programs. You’ll also learn what costs may remain, which eligibility details to verify, and how to shape a practical buying plan for your finances and the New Mexico communities you’re considering.
Key Takeaways
- Learn how to buy a house with no money down in New Mexico by comparing zero-down loan options with assistance programs that may help cover upfront expenses.
- Check whether VA or USDA financing may fit your situation, and verify current eligibility with a qualified lender or official program source.
- Build a realistic cash-to-close estimate that accounts for costs beyond the down payment, such as prepaid items, inspections, and moving expenses.
- Compare monthly payments and overall loan obligations, not just the amount due upfront.
- Prepare income, asset, debt, and identity records before discussing financing, then shape your home search around confirmed program terms and your budget.
What “no money down” means when buying a New Mexico home
Zero-down financing is a mortgage structure that may let an eligible borrower buy a home without making a down payment. It doesn’t mean the home costs nothing upfront, and not every buyer or property will qualify. For anyone researching how to buy a house with no money down in New Mexico, the first step is to separate the down payment from the other costs of purchasing and moving into a home.
Down payment assistance is a different tool. It may help with eligible upfront costs, but it can come with separate income, property, or borrower rules and may have repayment terms or other restrictions. Confirm the current details with an approved participating lender or the official program source before relying on assistance in your budget.
The video below discusses FHA financing, but its title alone doesn’t confirm that FHA loans require no down payment. Check loan claims and current terms with a qualified lender.
Does zero down mean buying a home costs nothing upfront?
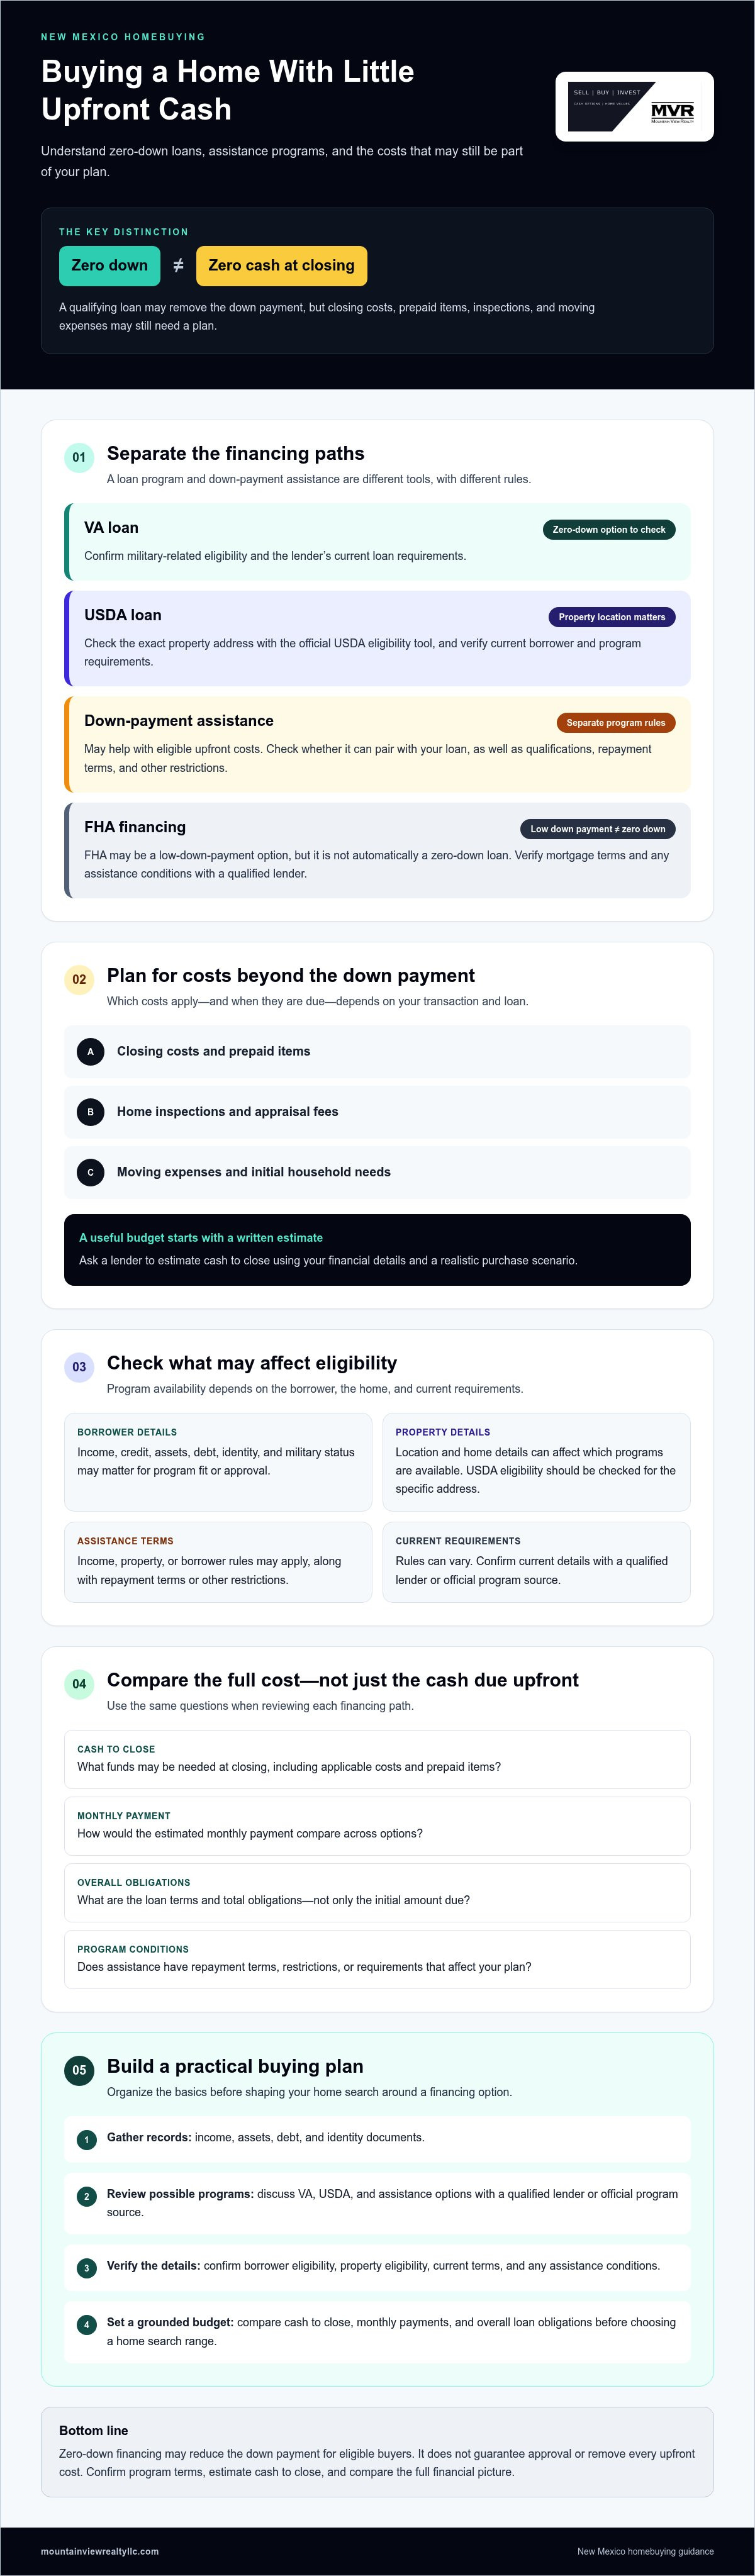
No. Even if your loan requires no down payment, your transaction or move may involve costs such as:
- Closing costs and prepaid items
- Home inspections and appraisal fees
- Moving expenses and initial household needs
Which costs apply, and when they’re due, depends on your transaction and loan. Ask a lender for a written estimate based on your financial details and a realistic purchase scenario. The Federal Housing Administration (FHA) loans overview explains FHA’s role in mortgage lending; FHA financing isn’t automatically zero down, so verify available terms with a lender.
Who may benefit from exploring low-down-payment options?
First-time buyers and people with limited savings may want to explore these options, but a low down payment doesn’t guarantee approval. Income, credit, military status, property location, and home details can affect which programs are available. A property’s USDA eligibility, for example, should be checked using the official address tool.
Compare the full picture, not just the amount due as a down payment. Ask how each option affects estimated cash to close, monthly payments, and total loan obligations. That comparison can help you judge whether a low-upfront-cost path fits your finances and homebuying plans.
Which zero-down and down-payment assistance options to check in New Mexico
To explore how to buy a house with no money down in New Mexico, compare loan programs with assistance programs. A loan program sets financing terms; assistance may help with eligible upfront funds, subject to its own rules. Neither category guarantees approval or means no cash will be needed.
| Option | What to check |
|---|---|
| VA loan | Whether you meet military-related eligibility requirements and the lender’s current loan requirements. |
| USDA loan | Whether the specific property address and borrower meet current program rules. |
| Down-payment assistance | Whether assistance can be paired with an eligible loan, and what qualifications and repayment terms apply. |
FHA financing can be a low-down-payment option, but it isn’t automatically a zero-down loan. If considering FHA financing with assistance, verify both the mortgage terms and the assistance conditions with a qualified lender.
Could a VA or USDA loan fit your circumstances?
VA and USDA financing are options to investigate, not guaranteed paths to approval. VA eligibility is tied to qualifying military service or status, so confirm your eligibility through official VA resources or a lender familiar with VA loans. USDA eligibility depends in part on the property’s location. Check the exact address with the current official USDA eligibility tool before assuming a home qualifies.
How can Housing New Mexico assistance fit into the search?
Start with the New Mexico Mortgage Finance Authority (MFA) for current state program information. Ask whether the program you’re considering is available, which loans it can accompany, and whether you must use a participating lender. Assistance may have its own borrower and property qualifications, and repayment conditions can vary by program. Review current program documents with the lender rather than relying on a general description.
When comparing options, ask for the estimated cash needed upfront and the expected monthly payment. Also confirm whether assistance changes your loan obligations or must be repaid under certain conditions. These details help you compare the whole purchase, not just the down payment.
Once a lender has clarified which financing paths may fit, a local real estate agent can help connect those parameters to your property search and transaction steps. If you’re planning a purchase in the Albuquerque area, you can discuss your home search and buying timeline with Mountain View Realty LLC.
How to compare zero-down options without overlooking the trade-offs
A low upfront payment can make a purchase more accessible, but it isn’t the only measure of affordability. As you consider how to buy a house with no money down in New Mexico, compare what each option means for your cash at closing, monthly budget, and longer-term loan obligations.
What should you compare beyond the down payment?
Ask lenders to prepare estimates for each option using the same purchase price and other assumptions. This makes it easier to see how the choices differ. Review:
- Estimated cash to close: Ask what funds may be due at closing and which costs, if any, assistance can cover.
- Monthly payment: Compare the estimated payment and its components, including any mortgage insurance that applies to the specific loan.
- Total loan obligations: Ask how the amount borrowed, loan costs, and assistance repayment terms affect your obligations over time.
- Program conditions: Check property restrictions, borrower qualifications, and whether assistance must be repaid under stated conditions.
A smaller down payment can affect the amount financed and borrowing costs, but the effect depends on the loan and your circumstances. Ask the lender to show how different down-payment choices would change your specific estimates. Avoid relying on a general promise of savings or assuming that a zero-down structure is automatically the least expensive option.
How do Albuquerque-area location and property choice matter?
Program rules can make property location important. A home in Albuquerque or nearby communities may be treated differently from a property elsewhere in New Mexico, depending on the loan or assistance program. For USDA financing, check the exact address with the current official eligibility resources, and review the USDA Rural Development loan information from USDA Rural Development. Address eligibility is only one part of determining whether a loan fits.
Keep the search flexible until your lender confirms how a particular property fits the program. Qualifying for a loan or assistance program doesn’t mean every home qualifies, or that every purchase and move-in expense is covered. Confirm the property requirements and what the assistance does and doesn’t pay for before making an offer.
Financing terms can also shape the home search itself. A buyer’s agent can help coordinate property-search and transaction steps around lender guidance. For more on choosing local representation, read how to choose a real estate agent in Albuquerque.
How to prepare for a New Mexico home purchase with little upfront cash
A clear sequence can help you move from financing questions to a focused home search without treating an unconfirmed program as part of your budget. For buyers exploring how to buy a house with no money down in New Mexico, start with your finances, then verify options before choosing homes to pursue.
- Review your finances. Take stock of income, savings and other assets, monthly debts, and the ongoing housing payment that feels manageable to you.
- Speak with lenders. Ask which loan or assistance paths may fit your verified situation, and what documents they need to assess it.
- Verify program and property rules. Confirm current availability, qualifications, assistance terms, and any property-location requirements through the lender and official program sources.
- Define your search criteria. Use the lender’s guidance alongside your own budget to set a practical price range, location, property type, and timeline.
Gather the income, asset, debt, and identity records your chosen lender requests. A complete set of information can help the lender assess your circumstances, but only the lender can explain what it means for a particular loan. Ask how long any preapproval information remains useful and what changes, such as a shift in income or debt, should prompt an update.
What should you ask a lender before viewing homes?
Get clear answers before building an offer plan around financing. Ask which zero-down or assistance options fit your documented circumstances, how the lender estimates cash to close and monthly obligations, and what conditions apply to any assistance. Confirm how long the preapproval information is current and which financial changes require the lender to review it again.
How can you plan a realistic Albuquerque-area home search?
Set a search range that reflects both lender guidance and your comfort with ongoing costs. Then discuss location, property type, and timing with a local real estate agent. As you compare homes across Bernalillo and Sandoval Counties, keep confirmed eligibility separate from assumptions. A lender or official program source should verify whether a specific property meets program rules before you rely on assistance in your offer plan.
Use this checklist to keep conversations organized:
- For the lender: Which options may fit? What records are needed? What are the estimated cash to close, monthly obligations, program conditions, and preapproval update requirements?
- For your real estate search: Which locations and property types fit your plan? What transaction dates should you discuss? Which property details still need lender or program confirmation?
Financing professionals can clarify loan approval and program terms. A local agent can help you align property search and transaction steps with that guidance.
Your next steps: verify financing, then build a New Mexico homebuying plan
Buying with no down payment may be possible for an eligible borrower using a qualifying loan. Down-payment assistance is separate and may have its own rules and repayment conditions. Neither option automatically covers every closing, prepaid, inspection, or moving expense. These distinctions are central to understanding how to buy a house with no money down in New Mexico, but your next step is to confirm how they apply to your situation.
Speak with a qualified lending professional about loan approval, estimated cash needed, monthly obligations, and current program terms. Ask for details in writing and confirm property requirements before including assistance in an offer plan. Mountain View Realty can help with local property-search and transaction steps, but it doesn’t provide mortgage lending or administer assistance programs.
When should you involve a local real estate agent?
Bring an agent into the process as you begin to shape your search. An agent can help align property choices, location priorities, and transaction steps with the guidance you receive from your lender. This is useful when program rules may affect which properties you can consider, or when you’re weighing options across Albuquerque and surrounding communities.
Robb Krautbauer brings 15 years of real-estate investing experience and 10 years as a licensed agent to his work with buyers and sellers. His role is to offer local real estate guidance, not to determine loan eligibility or promise a specific financing result.
What should your first homebuying conversation cover?
Start with the basics: where you hope to live, what matters most in a home, your preferred timeline, and the financing questions that remain after speaking with a lender. You might be comparing locations in Albuquerque, Rio Rancho, or elsewhere in the metro. Sharing your priorities can help focus the search while keeping unverified program assumptions separate from confirmed facts.
A thoughtful plan leaves room for questions and informed choices. You don’t need to settle on a home or a financing path before understanding the terms. Confirm loan approval and current assistance conditions with qualified lending professionals, then use that information to guide your search.
If you’re considering a purchase in the Albuquerque area, you’re welcome to discuss your priorities and buying timeline with Mountain View Realty. The conversation can help clarify local search and transaction steps without pressure.
Robb Krautbauer, Owner & Qualifying Broker
Build your next move on verified information
Zero-down financing can reduce the amount you need for a down payment, but it doesn’t automatically remove closing costs or other upfront expenses. Down-payment assistance is a separate option with its own current eligibility and terms. Compare estimated cash to close, monthly payments, and total loan obligations before choosing a path.
If you’re learning how to buy a house with no money down in New Mexico, start by confirming loan approval and program conditions with a qualified lender. Then use that guidance to shape a home search around your budget, preferred location, and priorities. A local real estate agent can help coordinate property-search and transaction steps, but isn’t a mortgage lender or program administrator.
Robb Krautbauer brings 15 years of real-estate investing experience and 10 years as a licensed agent. Mountain View Realty has helped 200+ families and investors buy and sell across the Albuquerque metro. Robb’s approach is educational and focused on helping you understand your choices.
You can take the next step at a pace that feels right, with verified financing information and a clear plan guiding your search.
Frequently Asked Questions
Is it possible to buy a house with no money down in New Mexico?
Yes, some eligible buyers may purchase a home with no down payment through programs such as VA or USDA financing. Eligibility depends on the buyer, loan, and property, and approval isn’t guaranteed. Also, zero down doesn’t necessarily mean no cash is needed for closing or other expenses. If you’re researching how to buy a house with no money down in New Mexico, ask a qualified lender to compare options and estimate your costs.
Can I use a USDA loan to buy a home in New Mexico with no down payment?
Possibly, if you and the property meet current USDA program requirements. USDA financing may offer eligible borrowers a zero-down option, but property location and household income can affect eligibility. Don’t assume a home qualifies based on its city or neighborhood. Check the exact address using USDA’s current eligibility resources, then ask a qualified lender to confirm borrower qualifications, loan terms, and any other requirements before relying on the program.
Can a VA loan help me buy a home with no down payment?
Yes, a VA loan may allow an eligible veteran, service member, or surviving spouse to buy with no down payment, subject to program and lender requirements. Your VA eligibility and entitlement matter, and the lender will review your finances and the property. Ask about any costs or loan conditions that may apply to your situation. Confirm eligibility and current terms with the U.S. Department of Veterans Affairs or a qualified VA lender.
Does buying a home with no money down mean I pay nothing at closing?
No. A zero-down loan addresses the down payment, not necessarily closing costs or other expenses. Depending on the transaction, buyers may also need to plan for prepaid items, an appraisal, inspections, or moving costs. Some assistance programs may help with certain upfront expenses, but coverage and terms vary. Ask your lender for a written estimate based on your financial details and a specific purchase scenario, and confirm which costs are included.
Can I get down-payment assistance in Albuquerque, New Mexico?
Possibly. New Mexico assistance programs may be available to eligible buyers in Albuquerque, but program availability, qualifications, lender participation, and terms can change. Start by reviewing current information from the New Mexico Mortgage Finance Authority and asking a participating lender which options fit your circumstances. Confirm whether assistance can be used with your loan and whether it has repayment conditions. Don’t include assistance in your purchase plan until its current terms are verified.
How do I find out whether a New Mexico home qualifies for a zero-down program?
Ask your lender to check the specific property against the loan program’s current requirements. For USDA financing, use the official USDA eligibility resources to check the exact address, then confirm the result with a qualified lender. Other programs may have different property rules. Location alone doesn’t confirm eligibility, and qualifying for a loan doesn’t mean every home or expense is covered. Verify the property and program conditions before making an offer based on assumed eligibility.
Article by
Robb Krautbauer
Robb Krautbauer is the Owner and Qualifying Broker of Mountain View Realty, serving Albuquerque, Rio Rancho, Santa Fe, and surrounding New Mexico communities. With more than a decade of real estate experience, Robb specializes in luxury homes, strategic home marketing, and helping homeowners navigate important life transitions with confidence.
Known for combining luxury-level marketing, AI-powered technology, and innovative selling strategies, Robb helps clients maximize their home's value while creating a smooth, personalized selling experience. Whether assisting luxury homeowners, retirees, families downsizing, or real estate investors, his focus is always on delivering expert guidance, honest advice, and exceptional results.
When he's not helping clients achieve their real estate goals, Robb enjoys studying market trends, emerging technology, and investment strategies that keep Mountain View Realty at the forefront of the industry.
Disclaimer
**Disclaimer:** The information provided in this article is for general educational purposes only and should not be considered legal, tax, financial, or professional advice. Real estate laws, market conditions, and regulations change over time and may vary based on your individual circumstances. Before making any real estate decision, consult with qualified legal, tax, or financial professionals. If you have questions about buying or selling real estate in New Mexico, contact Mountain View Realty for guidance specific to your situation. © 2026 Mountain View Realty. All rights reserved. The content on this website may not be reproduced without written permission.


